2023 Vehicle Purchase Tax Exemption Policies: Special Purpos
Date:2026-10-26
Page views:
What Are the Preferential Policies for Vehicle Purchase Tax in 2023?
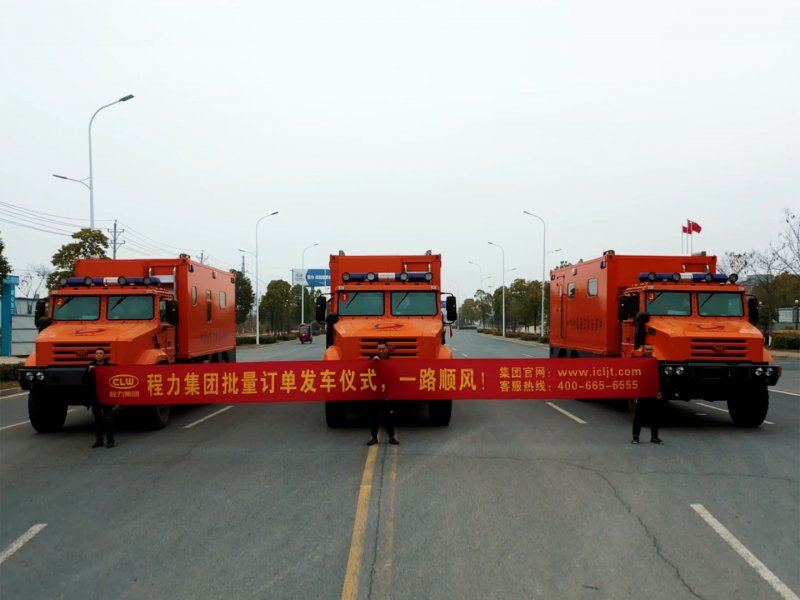
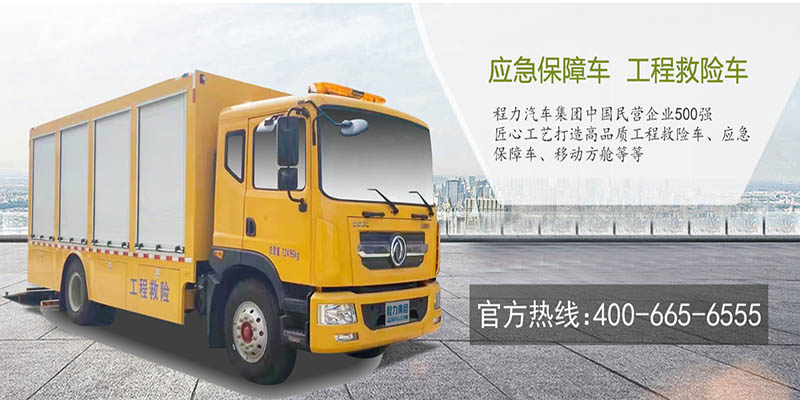
What are the preferential vehicle purchase tax reduction and exemption policies for special vehicles in 2023? First of all, special vehicles that fall into the tax-exempt vehicle category still enjoy the vehicle purchase tax exemption policy. Common special vehicles eligible for tax exemption include various water sprinkler trucks, dust suppression trucks, sewage suction trucks, fecal suction trucks, combined cleaning and sewage suction trucks, road sweepers, vacuum road sweepers, dust collection trucks, rescue vehicles, snow removal vehicles, guardrail cleaning vehicles, aerial work vehicles and other models. The above are common special vehicles exempt from vehicle purchase tax. Each special vehicle manufacturer can enjoy the preferential tax exemption policy after completing the tax exemption declaration. Therefore, when consumers purchase eligible tax-exempt special vehicle models, they need to confirm whether the tax exemption declaration of the selected announcement model has been completed. Only models with completed declarations can enjoy the corresponding vehicle purchase tax exemption policy during vehicle registration.
I. Vehicles Exempt from Vehicle Purchase Tax
(1) Statutory Preferences
In accordance with the provisions of the Vehicle Purchase Tax Law of the People's Republic of China, the following vehicles shall be exempt from vehicle purchase tax:
1. Vehicles for self-use by foreign embassies, consulates in China and offices of international organizations in China and their relevant personnel that shall be tax-exempt in accordance with the law;
2. Vehicles of the Chinese People's Liberation Army and the Chinese People's Armed Police Force included in the equipment order plan;
3. National comprehensive fire and rescue vehicles with special emergency rescue license plates;
4. Non-transport special operation vehicles with fixed installations;
5. Public buses and trolley buses purchased by urban public transport enterprises.
In light of the needs of national economic and social development, the State Council may stipulate circumstances for tax reduction or other vehicle purchase tax exemptions and file them with the Standing Committee of the National People's Congress for the record.
(2) Other Tax-Exempt Vehicles
1. One domestically-produced sedan purchased with foreign exchange for personal use by overseas Chinese students returning to serve in China, and one imported sedan for personal use by long-term foreign experts settling in China shall be exempt from vehicle purchase tax.
2. Vehicles of designated models manufactured by designated manufacturers with fixed installations used by flood control departments and forest fire prevention departments for command, inspection, scheduling, flood (alarm) reporting and communication shall be exempt from vehicle purchase tax.
3. Mobile medical vehicles under the "Healthy Mother Express" project of the China Women's Development Foundation shall be exempt from vehicle purchase tax.
4. Vehicles originally belonging to the active public security forces and the former armed police gold, forest and hydropower troops that have been reissued local motor vehicle license plates after institutional reform (excluding vehicles of public security fire control and armed police forest troops performing fire fighting and rescue tasks) shall be exempted from vehicle purchase tax on a one-time basis.
II. Policy-based Tax Reduction and Exemption Preferences
(1) Purchase of New Energy Vehicles
From January 1, 2018 to December 31, 2023, vehicle purchase tax shall be exempted for purchased new energy vehicles.
New energy vehicles exempt from vehicle purchase tax are administered through the Catalogue of New Energy Vehicle Models Exempt from Vehicle Purchase Tax (hereinafter referred to as the Catalogue) issued by the Ministry of Industry and Information Technology and the State Taxation Administration. New energy vehicles that meet the tax exemption conditions include pure electric vehicles, plug-in hybrid (including range-extended) vehicles and fuel cell vehicles listed in the Catalogue and purchased from the date of issuance of the Catalogue.
Note: The purchase date shall be determined based on the issuance date of valid vouchers such as the unified invoice for motor vehicle sales or the special customs duty payment receipt.
(2) Purchase of Trailers
From July 1, 2018 to June 30, 2021, vehicle purchase tax shall be levied at half the rate on purchased trailers. The purchase date shall be determined according to the issuance date of the Unified Invoice for Motor Vehicle Sales, the Special Customs Duty Payment Receipt or other valid vouchers.
Policy Basis:
1. Vehicle Purchase Tax Law of the People's Republic of China
2. Announcement of the Ministry of Finance and the State Taxation Administration on Continuing to Implement Preferential Vehicle Purchase Tax Policies (Announcement No. 75 of 2019 of the Ministry of Finance and the State Taxation Administration)
3. Announcement of the Ministry of Finance, the State Taxation Administration, the Ministry of Industry and Information Technology and the Ministry of Science and Technology on Exempting New Energy Vehicles from Vehicle Purchase Tax (Announcement No. 172 of 2017 of the Ministry of Finance)
4. Announcement of the Ministry of Finance, the State Taxation Administration and the Ministry of Industry and Information Technology on Policies Concerning the Exemption of New Energy Vehicles from Vehicle Purchase Tax (Announcement No. 21 of 2020 of the Ministry of Finance, the State Taxation Administration and the Ministry of Industry and Information Technology)
5. Announcement of the Ministry of Finance, the State Taxation Administration and the Ministry of Industry and Information Technology on Extending the Policy of Exempting New Energy Vehicles from Vehicle Purchase Tax (Announcement No. 27 of 2022 of the Ministry of Finance, the State Taxation Administration and the Ministry of Industry and Information Technology)
6. Announcement of the Ministry of Finance, the State Taxation Administration and the Ministry of Industry and Information Technology on Reducing Vehicle Purchase Tax on Trailers (Announcement No. 69 of 2018 of the Ministry of Finance, the State Taxation Administration and the Ministry of Industry and Information Technology)
Summary of Preferential Vehicle Purchase Tax Policies in 2023!
I. Vehicles Exempt from Vehicle Purchase Tax
(1) Statutory Preferences
In accordance with the provisions of the Vehicle Purchase Tax Law of the People's Republic of China, the following vehicles shall be exempt from vehicle purchase tax:
1. Vehicles for self-use by foreign embassies, consulates in China and offices of international organizations in China and their relevant personnel that shall be tax-exempt in accordance with the law;
2. Vehicles of the Chinese People's Liberation Army and the Chinese People's Armed Police Force included in the equipment order plan;
3. National comprehensive fire and rescue vehicles with special emergency rescue license plates;
4. Non-transport special operation vehicles with fixed installations;
5. Public buses and trolley buses purchased by urban public transport enterprises.
In light of the needs of national economic and social development, the State Council may stipulate circumstances for tax reduction or other vehicle purchase tax exemptions and file them with the Standing Committee of the National People's Congress for the record.
(2) Other Tax-Exempt Vehicles
1. One domestically-produced sedan purchased with foreign exchange for personal use by overseas Chinese students returning to serve in China, and one imported sedan for personal use by long-term foreign experts settling in China shall be exempt from vehicle purchase tax.
2. Vehicles of designated models manufactured by designated manufacturers with fixed installations used by flood control departments and forest fire prevention departments for command, inspection, scheduling, flood (alarm) reporting and communication shall be exempt from vehicle purchase tax.
3. Mobile medical vehicles under the "Healthy Mother Express" project of the China Women's Development Foundation shall be exempt from vehicle purchase tax.
4. Vehicles originally belonging to the active public security forces and the former armed police gold, forest and hydropower troops that have been reissued local motor vehicle license plates after institutional reform (excluding vehicles of public security fire control and armed police forest troops performing fire fighting and rescue tasks) shall be exempted from vehicle purchase tax on a one-time basis.
II. Policy-based Tax Reduction and Exemption Preferences
(1) Purchase of New Energy Vehicles
From January 1, 2018 to December 31, 2023, vehicle purchase tax shall be exempted for purchased new energy vehicles.
New energy vehicles exempt from vehicle purchase tax are administered through the Catalogue of New Energy Vehicle Models Exempt from Vehicle Purchase Tax (hereinafter referred to as the Catalogue) issued by the Ministry of Industry and Information Technology and the State Taxation Administration. New energy vehicles that meet the tax exemption conditions include pure electric vehicles, plug-in hybrid (including range-extended) vehicles and fuel cell vehicles listed in the Catalogue and purchased from the date of issuance of the Catalogue.
Note: The purchase date shall be determined based on the issuance date of valid vouchers such as the unified invoice for motor vehicle sales or the special customs duty payment receipt.
(2) Purchase of Trailers
From July 1, 2018 to June 30, 2021, vehicle purchase tax shall be levied at half the rate on purchased trailers. The purchase date shall be determined according to the issuance date of the Unified Invoice for Motor Vehicle Sales, the Special Customs Duty Payment Receipt or other valid vouchers.
Policy Basis:
1. Vehicle Purchase Tax Law of the People's Republic of China
2. Announcement of the Ministry of Finance and the State Taxation Administration on Continuing to Implement Preferential Vehicle Purchase Tax Policies (Announcement No. 75 of 2019 of the Ministry of Finance and the State Taxation Administration)
3. Announcement of the Ministry of Finance, the State Taxation Administration, the Ministry of Industry and Information Technology and the Ministry of Science and Technology on Exempting New Energy Vehicles from Vehicle Purchase Tax (Announcement No. 172 of 2017 of the Ministry of Finance)
4. Announcement of the Ministry of Finance, the State Taxation Administration and the Ministry of Industry and Information Technology on Policies Concerning the Exemption of New Energy Vehicles from Vehicle Purchase Tax (Announcement No. 21 of 2020 of the Ministry of Finance, the State Taxation Administration and the Ministry of Industry and Information Technology)
5. Announcement of the Ministry of Finance, the State Taxation Administration and the Ministry of Industry and Information Technology on Extending the Policy of Exempting New Energy Vehicles from Vehicle Purchase Tax (Announcement No. 27 of 2022 of the Ministry of Finance, the State Taxation Administration and the Ministry of Industry and Information Technology)
6. Announcement of the Ministry of Finance, the State Taxation Administration and the Ministry of Industry and Information Technology on Reducing Vehicle Purchase Tax on Trailers (Announcement No. 69 of 2018 of the Ministry of Finance, the State Taxation Administration and the Ministry of Industry and Information Technology)
What are the preferential vehicle purchase tax reduction and exemption policies for special vehicles in 2023? First of all, special vehicles that fall into the tax-exempt vehicle category still enjoy the vehicle purchase tax exemption policy. Common special vehicles eligible for tax exemption include various water sprinkler trucks, dust suppression trucks, sewage suction trucks, fecal suction trucks, combined cleaning and sewage suction trucks, road sweepers, vacuum road sweepers, dust collection trucks, rescue vehicles, snow removal vehicles, guardrail cleaning vehicles, aerial work vehicles and other models. The above are common special vehicles exempt from vehicle purchase tax. Each special vehicle manufacturer can enjoy the preferential tax exemption policy after completing the tax exemption declaration. Therefore, when consumers purchase eligible tax-exempt special vehicle models, they need to confirm whether the tax exemption declaration of the selected announcement model has been completed. Only models with completed declarations can enjoy the corresponding vehicle purchase tax exemption policy during vehicle registration.
I. Vehicles Exempt from Vehicle Purchase Tax
(1) Statutory Preferences
In accordance with the provisions of the Vehicle Purchase Tax Law of the People's Republic of China, the following vehicles shall be exempt from vehicle purchase tax:
1. Vehicles for self-use by foreign embassies, consulates in China and offices of international organizations in China and their relevant personnel that shall be tax-exempt in accordance with the law;
2. Vehicles of the Chinese People's Liberation Army and the Chinese People's Armed Police Force included in the equipment order plan;
3. National comprehensive fire and rescue vehicles with special emergency rescue license plates;
4. Non-transport special operation vehicles with fixed installations;
5. Public buses and trolley buses purchased by urban public transport enterprises.
In light of the needs of national economic and social development, the State Council may stipulate circumstances for tax reduction or other vehicle purchase tax exemptions and file them with the Standing Committee of the National People's Congress for the record.
(2) Other Tax-Exempt Vehicles
1. One domestically-produced sedan purchased with foreign exchange for personal use by overseas Chinese students returning to serve in China, and one imported sedan for personal use by long-term foreign experts settling in China shall be exempt from vehicle purchase tax.
2. Vehicles of designated models manufactured by designated manufacturers with fixed installations used by flood control departments and forest fire prevention departments for command, inspection, scheduling, flood (alarm) reporting and communication shall be exempt from vehicle purchase tax.
3. Mobile medical vehicles under the "Healthy Mother Express" project of the China Women's Development Foundation shall be exempt from vehicle purchase tax.
4. Vehicles originally belonging to the active public security forces and the former armed police gold, forest and hydropower troops that have been reissued local motor vehicle license plates after institutional reform (excluding vehicles of public security fire control and armed police forest troops performing fire fighting and rescue tasks) shall be exempted from vehicle purchase tax on a one-time basis.
II. Policy-based Tax Reduction and Exemption Preferences
(1) Purchase of New Energy Vehicles
From January 1, 2018 to December 31, 2023, vehicle purchase tax shall be exempted for purchased new energy vehicles.
New energy vehicles exempt from vehicle purchase tax are administered through the Catalogue of New Energy Vehicle Models Exempt from Vehicle Purchase Tax (hereinafter referred to as the Catalogue) issued by the Ministry of Industry and Information Technology and the State Taxation Administration. New energy vehicles that meet the tax exemption conditions include pure electric vehicles, plug-in hybrid (including range-extended) vehicles and fuel cell vehicles listed in the Catalogue and purchased from the date of issuance of the Catalogue.
Note: The purchase date shall be determined based on the issuance date of valid vouchers such as the unified invoice for motor vehicle sales or the special customs duty payment receipt.
(2) Purchase of Trailers
From July 1, 2018 to June 30, 2021, vehicle purchase tax shall be levied at half the rate on purchased trailers. The purchase date shall be determined according to the issuance date of the Unified Invoice for Motor Vehicle Sales, the Special Customs Duty Payment Receipt or other valid vouchers.
Policy Basis:
1. Vehicle Purchase Tax Law of the People's Republic of China
2. Announcement of the Ministry of Finance and the State Taxation Administration on Continuing to Implement Preferential Vehicle Purchase Tax Policies (Announcement No. 75 of 2019 of the Ministry of Finance and the State Taxation Administration)
3. Announcement of the Ministry of Finance, the State Taxation Administration, the Ministry of Industry and Information Technology and the Ministry of Science and Technology on Exempting New Energy Vehicles from Vehicle Purchase Tax (Announcement No. 172 of 2017 of the Ministry of Finance)
4. Announcement of the Ministry of Finance, the State Taxation Administration and the Ministry of Industry and Information Technology on Policies Concerning the Exemption of New Energy Vehicles from Vehicle Purchase Tax (Announcement No. 21 of 2020 of the Ministry of Finance, the State Taxation Administration and the Ministry of Industry and Information Technology)
5. Announcement of the Ministry of Finance, the State Taxation Administration and the Ministry of Industry and Information Technology on Extending the Policy of Exempting New Energy Vehicles from Vehicle Purchase Tax (Announcement No. 27 of 2022 of the Ministry of Finance, the State Taxation Administration and the Ministry of Industry and Information Technology)
6. Announcement of the Ministry of Finance, the State Taxation Administration and the Ministry of Industry and Information Technology on Reducing Vehicle Purchase Tax on Trailers (Announcement No. 69 of 2018 of the Ministry of Finance, the State Taxation Administration and the Ministry of Industry and Information Technology)
Summary of Preferential Vehicle Purchase Tax Policies in 2023!
I. Vehicles Exempt from Vehicle Purchase Tax
(1) Statutory Preferences
In accordance with the provisions of the Vehicle Purchase Tax Law of the People's Republic of China, the following vehicles shall be exempt from vehicle purchase tax:
1. Vehicles for self-use by foreign embassies, consulates in China and offices of international organizations in China and their relevant personnel that shall be tax-exempt in accordance with the law;
2. Vehicles of the Chinese People's Liberation Army and the Chinese People's Armed Police Force included in the equipment order plan;
3. National comprehensive fire and rescue vehicles with special emergency rescue license plates;
4. Non-transport special operation vehicles with fixed installations;
5. Public buses and trolley buses purchased by urban public transport enterprises.
In light of the needs of national economic and social development, the State Council may stipulate circumstances for tax reduction or other vehicle purchase tax exemptions and file them with the Standing Committee of the National People's Congress for the record.
(2) Other Tax-Exempt Vehicles
1. One domestically-produced sedan purchased with foreign exchange for personal use by overseas Chinese students returning to serve in China, and one imported sedan for personal use by long-term foreign experts settling in China shall be exempt from vehicle purchase tax.
2. Vehicles of designated models manufactured by designated manufacturers with fixed installations used by flood control departments and forest fire prevention departments for command, inspection, scheduling, flood (alarm) reporting and communication shall be exempt from vehicle purchase tax.
3. Mobile medical vehicles under the "Healthy Mother Express" project of the China Women's Development Foundation shall be exempt from vehicle purchase tax.
4. Vehicles originally belonging to the active public security forces and the former armed police gold, forest and hydropower troops that have been reissued local motor vehicle license plates after institutional reform (excluding vehicles of public security fire control and armed police forest troops performing fire fighting and rescue tasks) shall be exempted from vehicle purchase tax on a one-time basis.
II. Policy-based Tax Reduction and Exemption Preferences
(1) Purchase of New Energy Vehicles
From January 1, 2018 to December 31, 2023, vehicle purchase tax shall be exempted for purchased new energy vehicles.
New energy vehicles exempt from vehicle purchase tax are administered through the Catalogue of New Energy Vehicle Models Exempt from Vehicle Purchase Tax (hereinafter referred to as the Catalogue) issued by the Ministry of Industry and Information Technology and the State Taxation Administration. New energy vehicles that meet the tax exemption conditions include pure electric vehicles, plug-in hybrid (including range-extended) vehicles and fuel cell vehicles listed in the Catalogue and purchased from the date of issuance of the Catalogue.
Note: The purchase date shall be determined based on the issuance date of valid vouchers such as the unified invoice for motor vehicle sales or the special customs duty payment receipt.
(2) Purchase of Trailers
From July 1, 2018 to June 30, 2021, vehicle purchase tax shall be levied at half the rate on purchased trailers. The purchase date shall be determined according to the issuance date of the Unified Invoice for Motor Vehicle Sales, the Special Customs Duty Payment Receipt or other valid vouchers.
Policy Basis:
1. Vehicle Purchase Tax Law of the People's Republic of China
2. Announcement of the Ministry of Finance and the State Taxation Administration on Continuing to Implement Preferential Vehicle Purchase Tax Policies (Announcement No. 75 of 2019 of the Ministry of Finance and the State Taxation Administration)
3. Announcement of the Ministry of Finance, the State Taxation Administration, the Ministry of Industry and Information Technology and the Ministry of Science and Technology on Exempting New Energy Vehicles from Vehicle Purchase Tax (Announcement No. 172 of 2017 of the Ministry of Finance)
4. Announcement of the Ministry of Finance, the State Taxation Administration and the Ministry of Industry and Information Technology on Policies Concerning the Exemption of New Energy Vehicles from Vehicle Purchase Tax (Announcement No. 21 of 2020 of the Ministry of Finance, the State Taxation Administration and the Ministry of Industry and Information Technology)
5. Announcement of the Ministry of Finance, the State Taxation Administration and the Ministry of Industry and Information Technology on Extending the Policy of Exempting New Energy Vehicles from Vehicle Purchase Tax (Announcement No. 27 of 2022 of the Ministry of Finance, the State Taxation Administration and the Ministry of Industry and Information Technology)
6. Announcement of the Ministry of Finance, the State Taxation Administration and the Ministry of Industry and Information Technology on Reducing Vehicle Purchase Tax on Trailers (Announcement No. 69 of 2018 of the Ministry of Finance, the State Taxation Administration and the Ministry of Industry and Information Technology)